
Navia Weekly Roundup (Oct 12 – 16, 2026)
Week in the Review
Indian equity markets extended their rally for the second consecutive week, posting their strongest weekly gains since April. The rally was driven by strong buying in IT stocks amid upbeat Q2 earnings, appreciation in the rupee, and sustained support from domestic institutional investors (DIIs). The gains came despite elevated crude oil prices and continued selling by foreign institutional investors (FIIs).
Indices Analysis
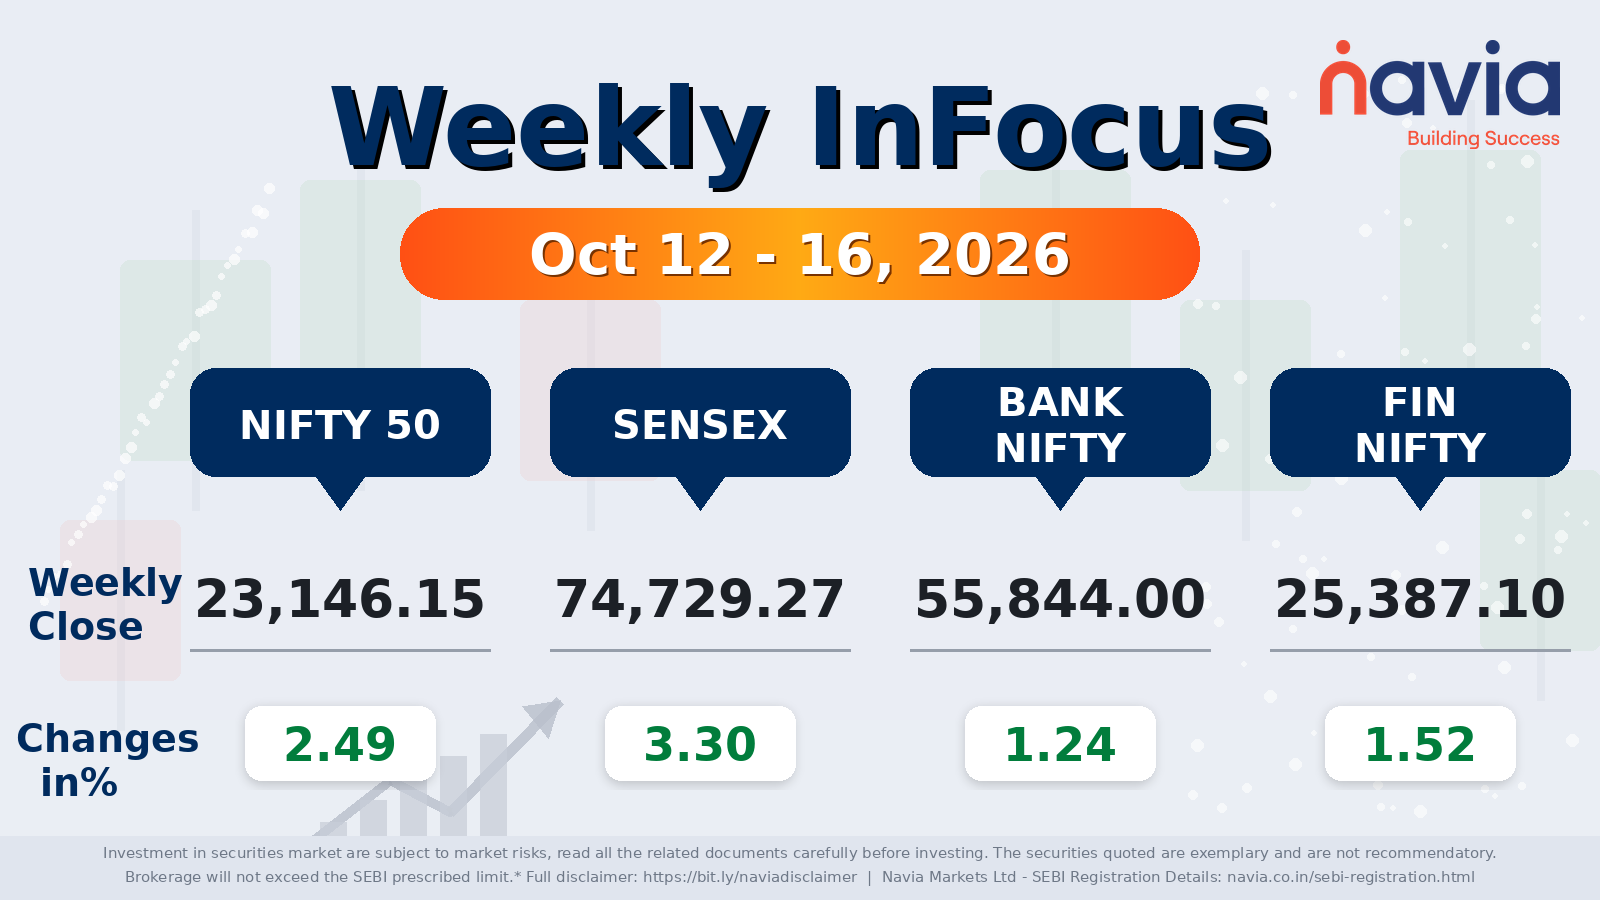
For the week, the Nifty 50 jumped 562.80 points, or 2.49%, to close at 23,146.15, while the BSE Sensex surged 2,387.26 points, or 3.30%, to end at 74,729.27. The Bank Nifty added 1.24% to 55,844.00, and the Fin Nifty advanced 1.52% to 25,387.10. India VIX eased 2.2%, while the broader market lagged the benchmarks, with the Midcap 100 up 0.6% and the Smallcap 100 marginally lower.
Information technology did the heavy lifting. The Nifty IT index surged 11.7%, its biggest weekly gain since April 2008, closing at 31,924.10 after a 3.92% jump on Friday, as better-than-expected September-quarter earnings reset the narrative for the sector. Managements flagged improving deal activity and AI-led demand, with Infosys CEO Salil Parekh saying AI services crossed 8% of revenue in Q2 and grew at a double-digit sequential rate, while doubts over returns on heavy AI infrastructure spending pushed global money towards established IT services firms. The rupee added its own tailwind, appreciating through the week after the RBI unveiled three support measures: a dedicated dollar window for public sector oil marketing companies, an open-market sale of ₹25,000 crore of government securities, and a requirement that banks maintain 99% of the prescribed cash reserve ratio daily from October 16.
The domestic backdrop stayed supportive. September CPI inflation came in at 5.54% year-on-year on Monday, within the RBI’s tolerance band after the October rate hike, the IMF raised its FY2026 growth forecast for India to 7% on October 13, and NPCI deferred the Merchant Discount Rate on select person-to-merchant UPI transactions until Diwali. Crude remained the chief worry, with Brent opening the week at $104.95 a barrel and touching $110 on Friday, while FIIs stayed sellers and DII buying continued to absorb the outflows. Outside the benchmarks, Yes Bank slumped after the Supreme Court quashed its appeal on the ₹8,415 crore AT1 bond write-off. Attention now turns to the unfolding Q2 earnings season and the WPI print in the coming week.
Interactive Zone!
Test your knowledge with our Markets Quiz! React to the options and see how your answer stacks up against others. Ready to take a guess?
Sector Spotlight
| Top Sector Gainers | Change | Top Sector Losers | Change |
|---|---|---|---|
| IT | +11.7% | Healthcare | -1% |
| Media | +6% | Pharma | -0.7% |
| Auto | +3% | FMCG | -0.55% |
| Realty | +2.7% | ||
| Defence | +2.2% |
Among sectoral indices, the Nifty IT index surged 11.7 percent, posting its biggest weekly gain in 18 years, driven by better-than-expected Q2 earnings. The Nifty Media index jumped more than 6 percent, while the Nifty Auto index gained 3 percent. The Nifty Realty and Nifty Defence indices advanced 2.7 percent and 2.2 percent, respectively. On the other hand, the Nifty Healthcare index declined 1 percent, while the Nifty Pharma and Nifty FMCG indices fell 0.7 percent and 0.55 percent, respectively.
Top Gainers and Losers
| Top Gainers | Change | Top Losers | Change |
|---|---|---|---|
| Tech Mahindra | +18.22% | Nestle India | -5.06% |
| TCS | +14.33% | Max Healthcare Inst. | -4.28% |
| Infosys | +13.46% | Interglobe Aviation | -3.02% |
| HCL Technologies | +13.42% | Larsen & Toubro | -2.06% |
| Bajaj Auto | +6.41% | Apollo Hospital Ent. | -1.71% |
Tech Mahindra led the gainers with an 18.22% surge on a Q2 beat, with TCS, Infosys and HCL Technologies all up over 13% as the IT rally lifted the entire pack, and Bajaj Auto rebounded 6.41% from its September-sales slide. On the losing side, Nestle India fell 5.06% despite a 36% jump in quarterly profit as it flagged food and commodity inflation pressures, Max Healthcare and Apollo Hospitals extended the healthcare slide, IndiGo slipped 3.02% on crude near $110, and Larsen & Toubro eased 2.06%.
Commodity Corner
| Commodity (MCX) | Weekly Close | Weekly Change |
|---|---|---|
| Gold (10g) | ₹1,45,894 | ▼ 2.02% |
| Silver (1kg) | ₹2,10,664 | ▼ 4.76% |
| Crude Oil (bbl) | ₹9,314 | ▲ 5.20% |
| Natural Gas (mmBtu) | ₹307.60 | ▲ 0.33% |
Energy diverged from precious metals. Crude oil rose 5.20% on MCX as Brent touched $110 a barrel, and natural gas edged up 0.33%, while gold slipped 2.02% and silver fell 4.76% as the equity rally cooled safe-haven demand.
Navia Blog Highlights
High Frequency Trading and the Retail Trader
High frequency trading moves markets in microseconds, and retail traders often wonder if they stand a chance against it. This explainer breaks down how HFT actually works, where it helps and hurts ordinary investors, and how to trade sensibly alongside the machines.
How India VIX Affects Options Trading
The fear gauge is an options trader’s weather report. This guide explains what India VIX measures, how rising or falling volatility reshapes option premiums, and how to use VIX levels to time strategies from straddles to covered calls.
N Coins Rewards
Refer your Friends & Family and get rewarded.
Did you find this article helpful?
Your feedback helps us write better content.
DISCLAIMER: Investment in securities market are subject to market risks, read all the related documents carefully before investing. The securities quoted are exemplary and are not recommendatory. Full disclaimer: https://bit.ly/naviadisclaimer.