
What Happens to Your Existing RI Demat Account After Becoming an NRI?
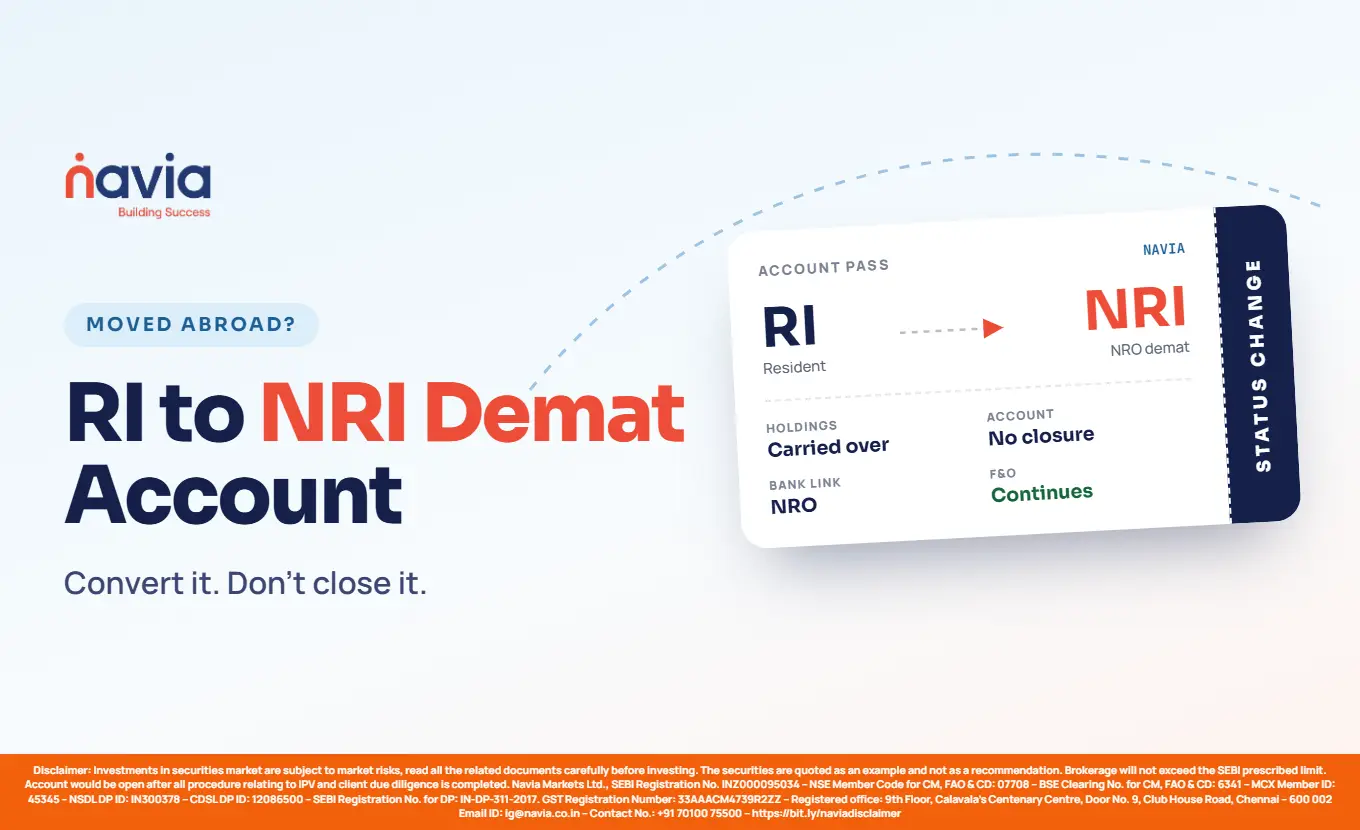
Moving abroad for work, studies or business is a big life change, and your Indian investments need to change with it. Many investors keep using their old resident (RI) trading and demat account after relocating, not realising that Indian regulations require the account status to be updated once they become a Non-Resident Indian (NRI).
The good news is that you no longer need to close your old account and start from scratch. At Navia, your existing resident account can be converted into an NRI Demat Account with the same holdings, through a simple documentation process.
Quick answer
Once you become an NRI, your resident demat account cannot continue as it is. It must be re-designated as an NRO Demat Account, and your resident savings account must become an NRO bank account. With Navia, you do not have to close your existing account: submit the RI to NRI status change documents, and your holdings, trading and even NRO F&O Trading continue under your new NRI status.
Key takeaways
- A resident demat account cannot continue unchanged once you become an NRI; it must be updated to NRI status.
- Your existing holdings move into an NRO Demat Account and are held on a non-repatriation basis.
- Navia converts your existing account without closure; you email [email protected], submit documents and courier the originals.
- An NRO PIS Bank Account is optional with Navia; a regular NRO savings account is enough.
- NRO F&O Trading can be enabled within one working day with simple income proof.
In this article
- Why must your resident demat account change after becoming an NRI?
- What happens to your existing holdings and positions?
- Resident demat account vs NRO demat account
- How do you convert your RI demat account to an NRI demat account with Navia?
- Do you need an NRO PIS bank account?
- NRO F&O trading after conversion
- Why choose Navia for your NRO trading and demat account?
- Conclusion
- Frequently Asked Questions
Why must your resident demat account change after becoming an NRI?
A resident demat account is opened under rules meant for people living in India. Once your residential status changes to NRI, your investments are governed by the Foreign Exchange Management Act (FEMA) and the related RBI guidelines for non-residents.
This means you should inform your broker and Depository Participant (DP) about the change in status and update your account. Continuing to trade through a resident account after becoming an NRI is not compliant and can lead to penalties, frozen accounts or problems when you later sell shares or move money.
Three things need to be updated together:
- Your PAN status must be categorised as NRI with the Income Tax Department.
- Your KYC must be updated with your overseas address and NRI status through the KRA.
- Your bank account linked for trading must be an NRO account instead of a resident savings account.

What happens to your existing holdings and positions?
This is the biggest worry for most new NRIs, so here is what changes and what stays the same.

- Your shares stay with you. Shares, ETFs and other securities bought while you were a resident are carried into your NRO Demat Account. They are held on a non-repatriation basis because they were bought with Indian funds.
- No need to sell before converting. You do not have to liquidate your portfolio. The status of the account changes; the holdings move with it.
- Your bank link changes. Your resident savings account must be re-designated as an NRO account with your bank, and that NRO account is linked to your trading account.
- Sale proceeds and dividends go to NRO. Money from selling these shares, and dividends on them, is credited to your NRO bank account. It can be repatriated abroad within the limits allowed for NRO funds, after applicable taxes.
- F&O can continue. NRIs can trade derivatives only on a non-repatriation basis, which is exactly what an NRO account allows. So NRO F&O Trading keeps your futures and options access alive after conversion.
- Taxes change. As an NRI, tax is deducted at source (TDS) on your capital gains. With Navia, TDS on NRO account trades is deducted by Navia at no extra cost.
- Nominee and contact details can be updated during the same process.
Resident demat account vs NRO demat account
The table below shows how your account changes once it is converted into an NRI Demat Account on the NRO route.
| Feature | Resident (RI) demat account | NRO demat account (after conversion) |
|---|---|---|
| Who can hold it | Resident Indians | NRIs (and OCIs, as applicable) |
| Linked bank account | Resident savings account | NRO savings account (PIS optional) |
| Existing holdings | Held as resident investments | Carried over, held on a non-repatriation basis |
| Repatriation | Not applicable | Allowed within NRO repatriation limits, after tax |
| Equity cash trading | Yes | Yes |
| F&O trading | Yes | Yes, through NRO F&O Trading |
| Intraday and BTST | Yes | Yes |
| Leverage and MTF | Yes | Yes |
| TDS on gains | Not applicable | Deducted by Navia at no extra cost |
| KYC address | Indian address | Overseas address, NRI status in KRA |
If you also earn abroad and want to invest that money with free repatriation, you can open an NRE demat account alongside. Read our guide on the difference between NRE and NRO accounts to decide.
How do you convert your RI demat account to an NRI demat account with Navia?
Earlier, NRIs had to close their resident account and open a fresh one. With Navia’s RI to NRI Status Change, your existing trading and demat account is converted to NRI status without closure, once the documentation and approvals are complete.
Who should apply?
- You were previously a Resident Indian.
- You have become an NRI and now live outside India.
- You want to keep investing and trading through your existing Navia account.
Documents required
- PAN Card (categorised as NRI)
- Passport
- Valid Visa / Work Permit / Residence Permit / OCI card, as applicable
- Overseas address proof
- NRE/NRO bank proof or bank statement
- Nominee proof, if nominee details are being updated
- Signed account modification forms: NRI KYC Form with FATCA Declaration, Category Change Form and Segment Enable Form (available on the Navia support page)
Step-by-step conversion process


Do you need an NRO PIS bank account?
A Portfolio Investment Scheme (PIS) account is a bank account designated by RBI for NRIs to buy and sell shares, with every trade reported to the bank. For an NRE demat account, a PIS account is mandatory.
For an NRO Demat Account, an NRO PIS Bank Account is optional. With Navia, you can link your regular NRO savings account directly, which means:
- No separate PIS bank account to open
- No PIS transaction charges levied by the bank
- You can link multiple NRO bank accounts to one trading account
- Funds can be added online through the payment gateway
Want to understand the two routes better? Read the difference between a PIS and a non-PIS account.
NRO F&O trading after conversion
Futures and options are open to NRIs only through the NRO route, not through NRE. Once your account is converted, enabling NRO F&O Trading with Navia is simple:

Navia activates derivatives trading within one working day of receiving your request and documents.
Why choose Navia for your NRO trading and demat account?
When you convert to an NRI Demat Account, the NRO route with Navia gives you nearly the same flexibility you had as a resident, at a low cost. Here’s why Navia stands out:
For more details, visit Navia’s NRI Demat Account page.
Conclusion
Becoming an NRI does not mean giving up your Indian portfolio. It means updating your account so it stays compliant. By converting your resident account into an NRO Demat Account, you keep your existing holdings, continue trading, and retain access to F&O, intraday and leverage. With Navia’s RI to NRI Status Change, the process is handled without closing your account, backed by a dedicated NRI team.
Educational content, not investment or tax advice. Confirm your residential status and tax position with a qualified adviser.
Did you find this article helpful?
Your feedback helps us write better content.
Frequently Asked Questions
What happens to my demat account when I become an NRI?
Your resident demat account must be converted to NRI status. The holdings you bought as a resident are carried into an NRO Demat Account and held on a non-repatriation basis.
Do I need to close my resident demat account and open a new NRI Demat Account?
No. With Navia, your existing trading and demat account is converted to NRI status without closure, once the required documents and approvals are complete.
Do I have to sell my shares before converting?
No. Your shares stay in your account and move to NRO status. You can continue to hold or sell them after conversion.
Can I trade F&O after converting to an NRO Demat Account?
Yes. NRIs can trade derivatives on a non-repatriation basis through an NRO account. Navia enables NRO F&O Trading within one working day after you email [email protected] with income proof.
Is an NRO PIS Bank Account mandatory?
No. PIS is mandatory only for NRE demat accounts. With Navia, you can link any regular NRO savings account and avoid PIS charges.
Can I open an NRE demat account as well?
Yes. If you want to invest foreign earnings with free repatriation, you can hold an NRE demat account alongside your NRO Demat Account.
How long does the RI to NRI conversion take?
It depends on document verification, KRA registration and regulatory approvals. Navia’s NRI team keeps you informed throughout.
RISK DISCLOSURES ON DERIVATIVES: 9 out of 10 individual traders in the equity Futures & Options segment incurred net losses. On average, loss-makers registered a net trading loss close to ₹50,000. Over and above the net trading losses, loss-makers expended an additional 28% of net trading losses as transaction costs. Those making net trading profits incurred between 15% and 50% of such profits as transaction cost. (Source: SEBI study dated January 25, 2023.)
DISCLAIMER: Investment in securities market are subject to market risks, read all the related documents carefully before investing. The securities quoted are exemplary and are not recommendatory. Brokerage will not exceed the SEBI prescribed limit. Full disclaimer: https://bit.ly/naviadisclaimer